
Updated and policy-checked 26 October 2026.
Australia's May 2026 property-tax reforms are no longer just a Budget proposal.
The core law is enacted, but the main CGT and residential rental-loss changes
apply from 1 July 2027. Later amendments and an October Bill mean investors
need to distinguish enacted rules from proposed detail.
For a NSW buyer, the first task is to separate two questions: when was the
ownership interest acquired, and when did the capital gain accrue? The
negative-gearing grandfathering date does not freeze all future CGT treatment.
Neither date is a reason, by itself, to rush a purchase or sale.
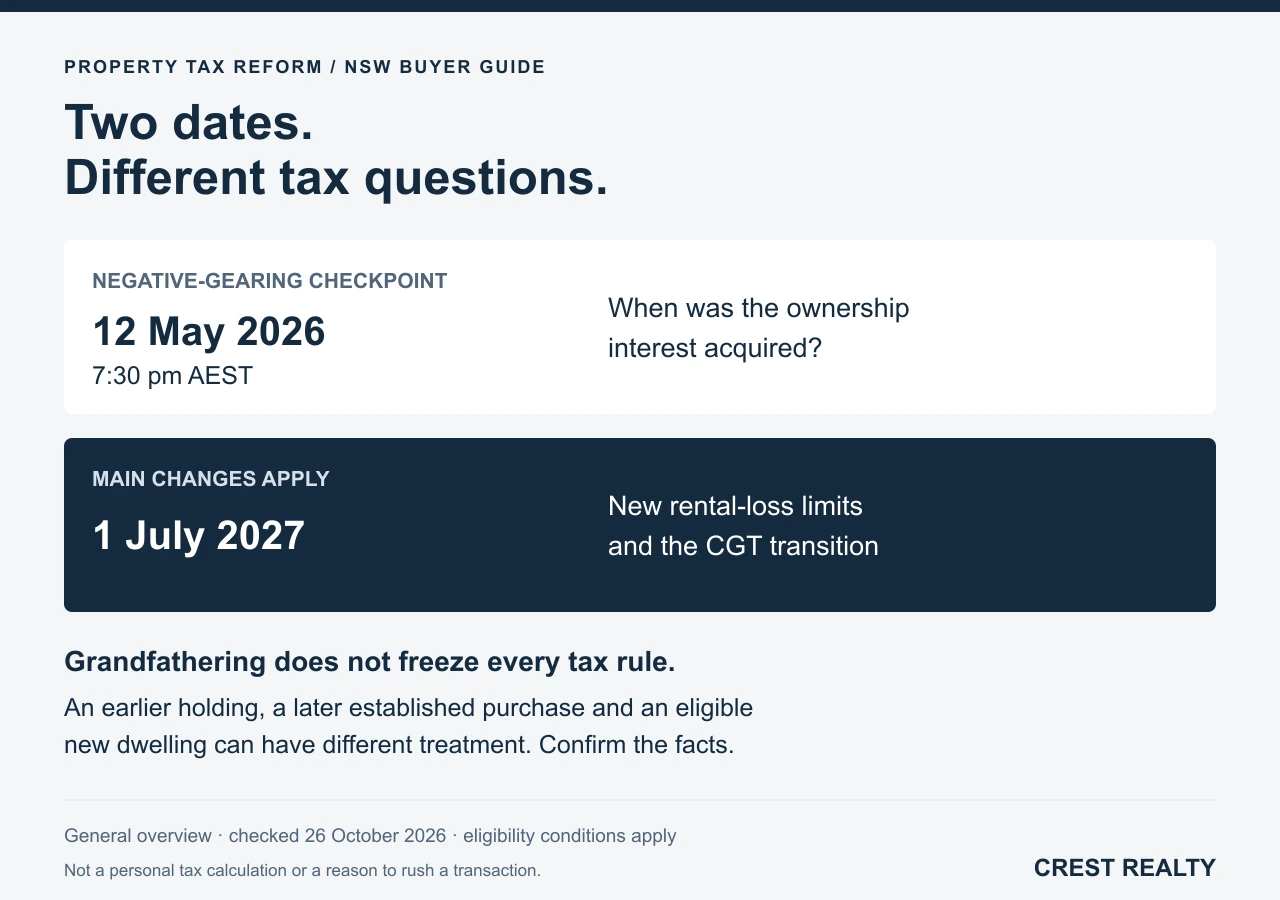
What is law, and what is still a proposal?
| Milestone | Status at the checked date | Why it matters |
|---|---|---|
| 12 May 2026, 7:30 pm AEST | Announcement-time checkpoint in the enacted rules. | Relevant to grandfathering of established residential ownership interests; it is not the general CGT transition date. |
| 26 June 2026 | Tax Reform No. 1 Act received Royal Assent. | Core CGT and negative-gearing reforms legislated, with their own commencement and application rules. |
| 26 August 2026; amendments commencing 1 October 2026 | Tax Reform No. 2 Act enacted. | Added conditional rules for certain deaths, relationship breakdowns and existing-home tax interactions. It did not move the main 2027 application date. |
| 14 October 2026 | Tax Reform No. 3 Bill introduced; still before the House of Representatives. | Further definitions and technical treatment remain proposals, including the new-residential-dwelling framework. |
| 1 July 2027 | Future application date for the principal property changes. | Compare the transition period with 2027–28 and later years; do not apply all the new rules to today's return. |
The No. 1 Act and
No. 2 Act are law.
The current Parliament record for the No. 3 Bill
shows it before the House. The Treasurer's 14 October release
describes its proposed definitions and exemptions. A Bill, consultation paper
or marketing summary is not a final property-eligibility decision.
Negative gearing: acquisition timing changes the comparison
Treasury's reform overview
explains the core direction: preserve earlier holdings, restrict the use of
losses on later established purchases and retain support for eligible new supply.
| Property situation | Position to check from 1 July 2027 | Practical question |
|---|---|---|
| Established residential interest acquired before the announcement checkpoint | Generally grandfathered from the new loss-quarantining rule, subject to the facts and any later ownership changes. | Does the actual interest, contract and ownership history satisfy the exception? |
| Established residential interest acquired after that checkpoint | Net rental losses generally cannot reduce wages or other non-residential income; residential-property income/gain and carry-forward rules apply. | Can the budget support the property without assuming a wage-income tax refund? |
| Eligible new residential dwelling | An exception can preserve negative gearing, but the dwelling must qualify in relation to the investor. | What final legal test and documentary evidence establish eligibility? |
| A home bought to live in | The owner's household budget and use of the home drive the decision. | Can you afford repayments and ownership costs, and satisfy any separate buyer-assistance rules? |
For established purchases after announcement and before 1 July 2027, current
arrangements can still operate during the transition. Buying before July 2027
does not move the grandfathering checkpoint forward. The
Budget transition explainer
also distinguishes continuing deductions on earlier holdings from later
established purchases.
Quarantining is generally a restriction on when and against which income
a loss is used, not permission to deduct every outgoing. Private expenditure,
loan principal and amounts of a capital nature need their own treatment.
Ownership structures, special housing uses and multiple-property portfolios
can produce different results; have your tax adviser apply the actual rules.
August amendments: do not assume a transfer always loses protection
Schedule 4 of the No. 2 Act
adds conditional provisions for a surviving spouse, certain interests received
when a non-spouse co-owner dies, and specified relationship-breakdown transfers.
It also addresses interactions with the rule for a home first used to produce
income. Certain preserved new-dwelling treatment can flow through to CGT.
These are targeted provisions, not a blanket inheritance or divorce exemption.
The parties, earlier acquisition dates, ownership interests, transfer mechanism
and dwelling's status matter. If estate planning, separation or a change of use
is involved, obtain advice before treating the transaction like an ordinary sale
or assuming all concessions transfer unchanged.
A property called “new” is not automatically an eligible new build
The October Bill announcement
includes a new-residential-dwelling definition and proposed exemptions for
specified housing activities. The earlier Treasury consultation materials
also address these questions. Their status must remain distinct from enacted law.
For a particular apartment, house-and-land purchase or redevelopment, ask for
evidence of construction/completion, title and contract dates, first-sale and
occupation history, the interest being bought and any additional-supply test.
Have an adviser check those facts against the final applicable law. A “new”,
“off-the-plan” or “never lived in” label does not, on its own, answer that test.
This is also separate from NSW new-home grant eligibility and federal
owner-occupier deposit schemes. A property or buyer qualifying under one
program does not establish investor-tax eligibility under another.
CGT: a separate transition, not a flat tax on every sale
The Budget CGT explanation
describes replacing the general 50% discount for relevant post-1 July 2027 gains
with cost-base indexation. The transition generally separates pre-date gains
from later gains when realised. It is not an annual tax bill simply because a
home's value has risen. Eligible new-dwelling investors can have a different
choice of treatment, subject to the rules.
The enacted minimum-tax provisions
also need care: the 30% mechanism concerns relevant gains of Australian-resident
individuals, including relevant trust-beneficiary gains, and has statutory
exceptions. It is a minimum-tax calculation, not a universal final rate of
30% on sale proceeds or every nominal profit. Do not apply one headline rate
to a company, super fund, trust or individual without checking the structure.
Ask your adviser how the transition value, permitted allocation method,
capital losses, eligible cost base and any earlier deductions interact. Keep
contracts, improvement invoices, ownership/use records and appropriate valuation
evidence; a depreciation schedule and a market valuation serve different jobs.
The main-residence exemption remains relevant, but rental, business or mixed-use
history can require a separate calculation.
A hypothetical cash-flow check, with no promised tax refund
Assume one investment, an annual period and these illustrative amounts only:
| Item | Assumed amount |
|---|---|
| Rent received | $36,000 |
| Cash expenses, all assumed deductible for this illustration | $42,000 |
| Cash shortfall before principal repayments, capital spending and tax | $6,000 |
| Additional eligible non-cash depreciation deductions, assumed | $4,000 |
| Illustrative taxable rental loss | $10,000 |
The arithmetic is $36,000 minus $42,000 = a $6,000 cash shortfall, and then
minus $4,000 = a $10,000 tax loss. Those are different numbers. The example
does not establish any expense's deductibility or depreciation entitlement.
For a post-announcement established property subject to quarantining from
2027–28, do not assume the $10,000 loss creates an immediate salary-tax refund.
Whether it can be used against residential income/gains or carried forward
depends on the rules and other facts. Even where a deduction can be used,
it does not reimburse the entire expense. Budget for the cash gap and debt
repayments separately.
The ATO rental-property guide
explains immediate expenses versus claims over several years. Our
depreciation and negative-gearing guide
provides context, while your tax agent determines the actual claims. Use the
mortgage repayment calculator and
buying-cost calculator as planning worksheets;
neither calculates this reform's personal tax result.
What buyers and landlords can do now
- Before purchasing: record the exact contract/interest-acquisition date,
check the property's legal category and have finance, contract and tax advice
considered together. Compare the property on location, build quality, price,
completion risk and tenant demand as well as any tax treatment. - Before relying on a refund: model holding costs and repayments through
2027–28 with vacancy, repairs and interest-rate pressure. Get the tax adviser
to identify which assumptions survive the reform. - Before selling or transferring: compare net proceeds, transaction costs,
household/portfolio objectives and the tax result. The reform is not an
instruction for every existing landlord to sell. - For a first home: prioritise affordability and suitability. Changes in
investor demand do not establish a guaranteed discount, a rent outcome or
future capital growth for a particular Sydney suburb.
Plan the property decision with the right advisers
Explore buying with Crest Realty or our land and house-and-land projects
once your advisers have clarified the funding and tax assumptions. Existing
landlords can review our property management services.
Current property details and availability need confirmation; no Crest project
is represented as automatically qualifying for a tax exception.
Contact Crest Realty about your property requirements. We can
discuss the property and transaction information; your registered tax agent,
legal adviser and lender determine the advice and approvals relevant to you.
General information only, checked 26 October 2026. This is not personal tax,
financial, legal, credit or investment advice. Law, Bill status and guidance can
change. Obtain advice for your ownership, dates, property and circumstances
before committing. Recheck the official sources when making the decision.